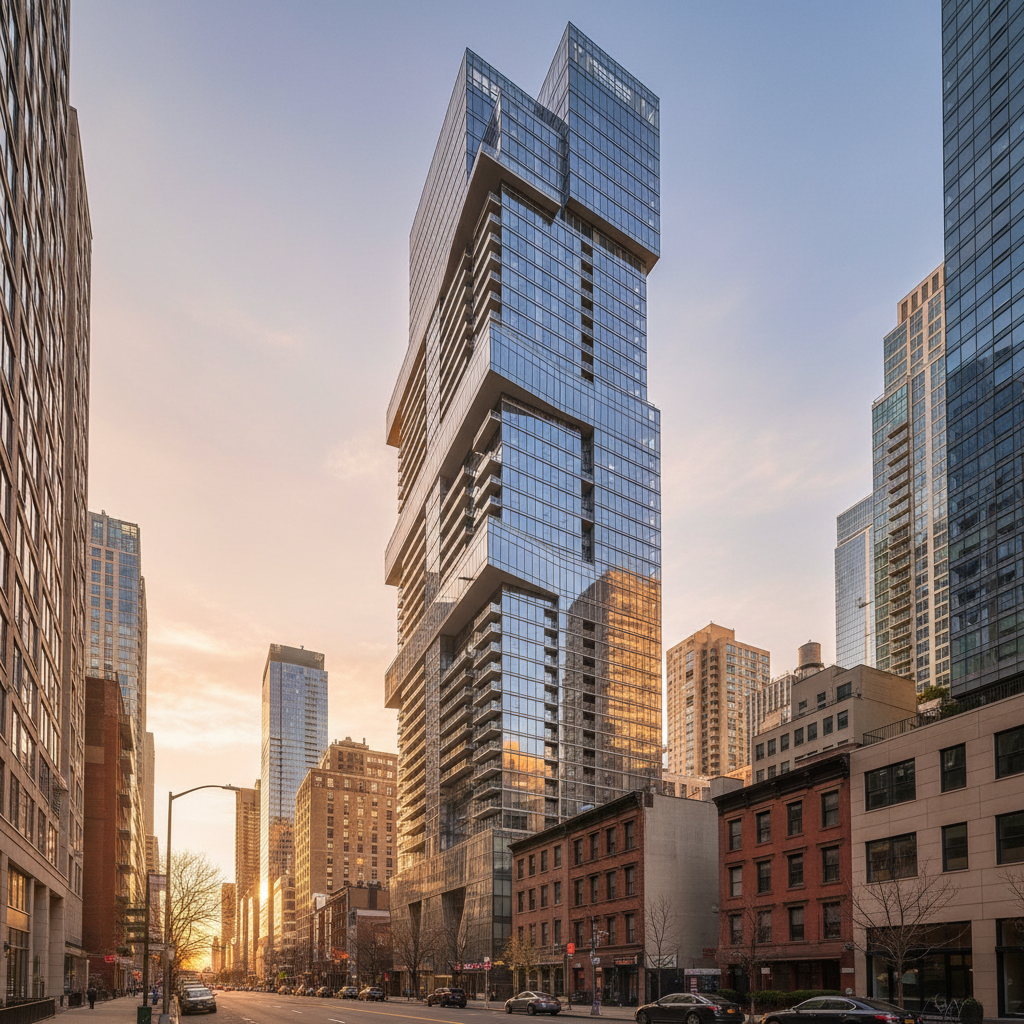
A condo carried at $1,000,000 of Department of Finance valuation owes about $40,000 a year in New York's new pied-a-terre surcharge if it is not a primary residence. That cost sits on top of a building-rules question that decides where a second-home buyer can shop at all: most NYC condos permit a pied-a-terre, while many co-op boards either prohibit part-time occupancy outright or approve it only with a larger down payment and one to two years of post-closing liquidity. In my 25+ years working in Manhattan real estate, I check a building's house rules before my clients invest time in an application. Below: the building rules, how financing differs, and where the surcharge fits into the carrying cost.
What Is a Pied-a-Terre?
A pied-a-terre is a secondary residence used for occasional stays rather than as a primary home. The distinction matters because NYC taxes non-primary residences differently, and many co-op buildings restrict or prohibit part-time use.
Co-op vs. Condo for a Pied-a-Terre
Condo: Pied-a-Terre Friendly
- No board approval required for purchase
- No restrictions on non-primary residence use
- Easier financing for second homes
- Can sublet or rent when not using
- Higher price per square foot
Co-op: Significant Restrictions
- Many boards prohibit pied-a-terre use
- Board interview required, can reject
- Subletting typically limited or banned
- May require full-time occupancy
- Lower price per square foot
Condos are the practical choice for most second-home buyers. Some prewar co-ops in prime Manhattan locations do allow pied-a-terre purchases, so the specific building's house rules decide. For a deeper comparison, see my co-op vs. condo guide.
Tax Implications for Pied-a-Terre Owners
No STAR Exemption
The STAR school tax relief exemption is only available for primary residences, so pied-a-terre owners pay the full property tax without that discount.
No Capital Gains Exclusion
When you sell a primary residence, you can exclude up to $250,000 ($500,000 for married couples) in capital gains from federal taxes under IRC Section 121. A pied-a-terre does not qualify for this exclusion. All gains are taxable at the applicable capital gains rate.
Manhattan Luxury Condos
Condos $1M+ ideal for pied-à-terre buyers
View All
Listing information provided courtesy of the Real Estate Board of New York's Residential Listing Service (RLS).
Information is deemed reliable but not guaranteed. Sale listings verified.
©2026 REBNY. RLS data displayed by Keller Williams NYC.
The pied-a-terre tax
This is no longer a proposal. New York enacted the surcharge on May 27, 2026 as part of the state budget, and it now sits in the Tax Law as Article 30-C, sections 1350 through 1356, officially the city surcharge on property that does not serve as a primary residence. It applies to city fiscal years starting July 1, 2026, the first charges land on the property tax bill due January 1, 2027, and the law sunsets June 30, 2031 unless Albany renews it. Unlike the mansion tax, which you pay once at closing, this one comes back every year you own the home.
The threshold is the city's valuation, not your sale price
This is the detail that trips up almost every buyer I talk to. In Phase 1, from July 1, 2026 through June 30, 2028, the thresholds are measured against the Department of Finance valuation printed on the property tax bill, not against what the home would sell for. One-to-three-family houses are covered above a $5,000,000 Department of Finance valuation. Condo and co-op units are covered above a $1,000,000 Department of Finance valuation, which sounds far lower until you know why: the city values apartments using a rental-income method that runs well below market prices. The Department of Finance itself says a condo or co-op it values at $1,000,000 is generally comparable to a single-family home valued at $5,000,000 or more. Pull the valuation off the tax bill before you assume a unit is or is not covered.
What it costs, and where the full rules live
There is no marginal calculation. Once a property crosses a tier, the rate applies to the entire valuation, so a condo carried at exactly $1,000,000 of city valuation owes about $40,000 a year and a non-primary house valued at $20,000,000 owes $210,000. Starting July 1, 2028, Phase 2 is written to move condos and co-ops onto the same $5,000,000 threshold as houses under a new Department of Finance assessed-value system that has not been finalized, so treat Phase 2 as scheduled rather than settled.
The full rate table, the five exemption paths, the accepted proof, the October 6, 2026 response deadline for anyone who got a July 22 notice, and the litigation all sit on one page: the NYC pied-a-terre tax page. Read it before you bid on a second home. If you already own a covered unit, the exemption check answers whether the surcharge reaches you at all.
What This Means If You Are Buying Now
If the home will not be a primary residence for you, a tenant, or a qualifying family member, this surcharge is a fixed annual carrying cost and belongs in your budget next to common charges and property tax. It also changes what you should pay: the city projects roughly $500 million a year from roughly 10,000 properties, and every future buyer of a covered unit has to underwrite the same number, which shows up in resale pricing. Model it before you bid, alongside the one-time mansion tax in the mansion tax calculator. If you already own a unit the surcharge reaches, the sell or lease calculator prices the three ways out of it.
Mansion Tax (Already in Effect)
Separate from the annual pied-a-terre surcharge above, the 2019 expanded NYC Mansion Tax already applies to all luxury residential sales regardless of occupancy status. The tax is graduated from 1.0% to 3.9%, with the top bracket of 3.9% applying to residential sales above $25 million. Some buildings impose private rules on non-resident owners (higher common charges, stricter sublet caps), but those are building-level matters, not government taxes. For the full breakdown, see my NYC mansion tax guide.
LLC and Trust Ownership
Some pied-a-terre buyers purchase through an LLC or trust to keep ownership out of public records. NYC requires disclosure of beneficial owners on all residential purchases over $300,000, and most co-ops do not permit LLC purchases. The enacted pied-a-terre tax adds another layer: it looks through entities, so a majority LLC or partnership member, or the sole beneficiary of a trust, is treated as the owner for the surcharge. Consult a real estate attorney before choosing an ownership structure, especially for purchases above $5 million.
Financing a Pied-a-Terre
Lenders treat a second home differently from a primary residence, and the occupancy label has to be true. Under Fannie Mae's rules, a second home must be a one-unit dwelling, the borrower must keep sole control of it, and it cannot be a rental property or a timeshare. If you plan to rent the unit out, tell your lender up front, because it changes the loan category. Down payment, reserve, and rate terms for second homes are set by each lender, so get a written quote before you bid. Many pied-a-terre buyers pay all cash, especially at the luxury end, which avoids the financing questions and speeds up closing. Read my mortgage pre-approval guide for more on lender requirements.
Best Property Types for a Pied-a-Terre
Look at studios and one-bedrooms in full-service condo buildings in Midtown, the Upper East Side, and the Financial District. Doorman service, in-unit laundry, and proximity to your office matter most for occasional use.
Bottom Line
A pied-a-terre follows different rules than a primary residence: less favorable tax treatment, stricter lending categories, and building restrictions that can narrow your options. I help pied-a-terre buyers at Keller Williams NYC find the right building and structure the deal. Reach out if you want to start the conversation.
Sources
Primary sources for the figures on this page, verified September 1, 2026.
Get NYC market insights delivered to your inbox
New listings, market data, and expert analysis. No spam.
We respect your privacy. Unsubscribe at any time.