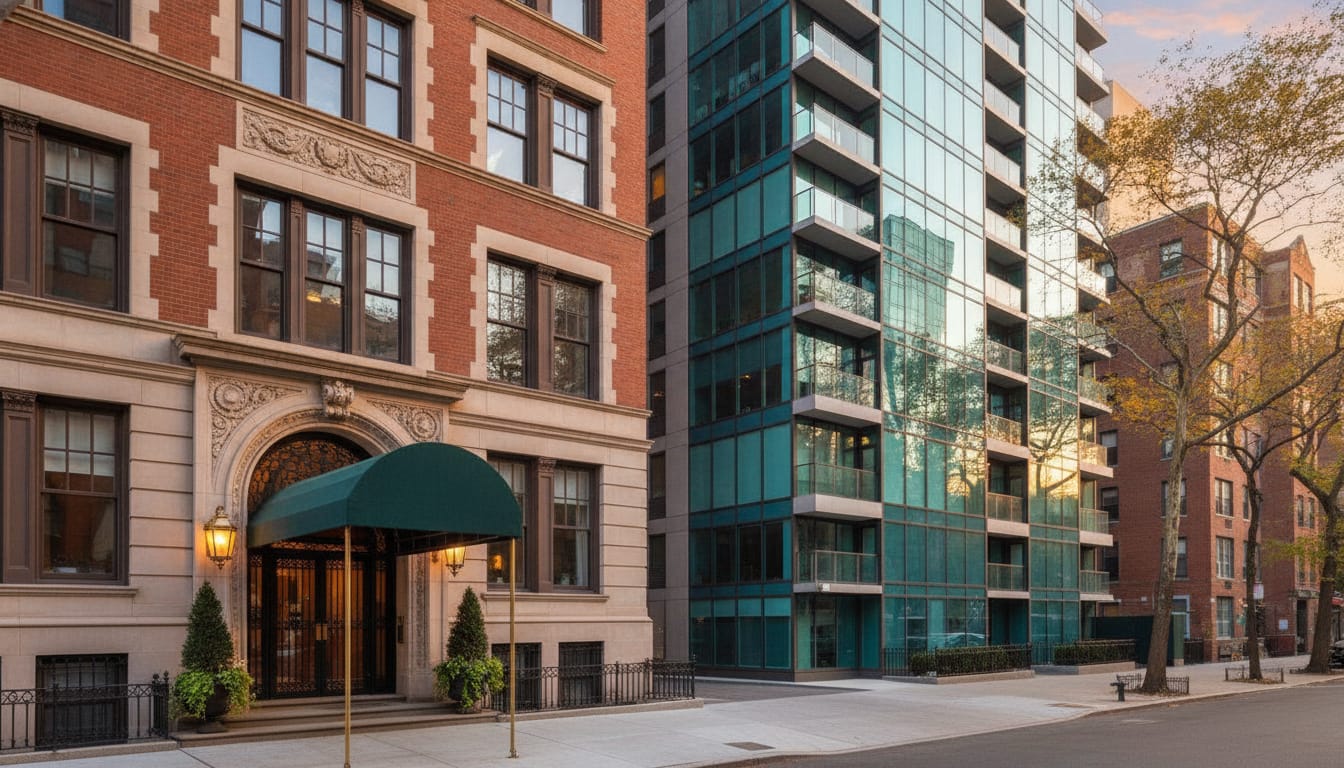
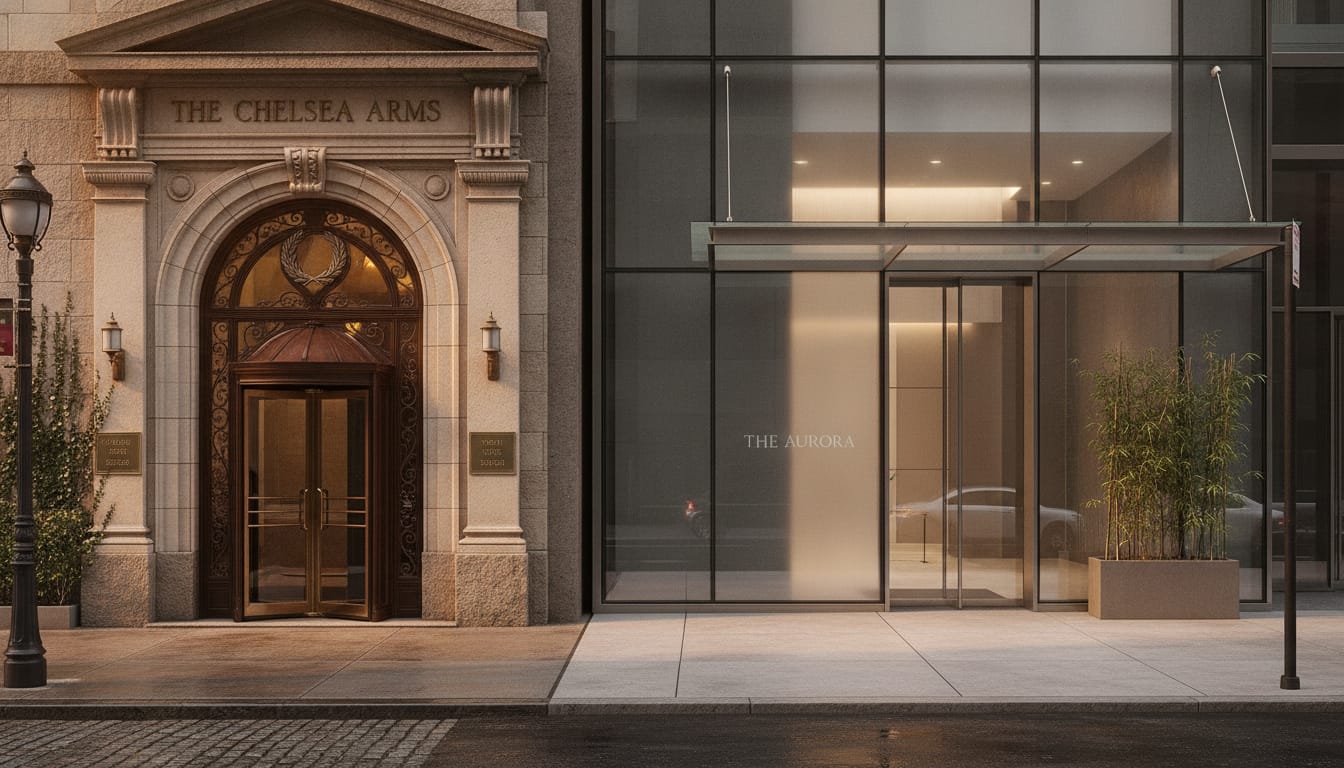
Condo vs Co-op Above $2M in NYC: What Changes for Buyers
Entity purchases, second-home and sublet policies, board liquidity tests, and what the public record shows after you close.
Milton Coste, Licensed Real Estate Associate Broker•Keller Williams NYC•NY Lic. #10301213304
August 27, 2026• 9 min read•25+ Years Experience
Above $2M in NYC, the ownership structure sets the rules: a condo is deeded real property that can usually be titled to an LLC or trust and rented out, while a co-op is shares in a corporation whose bylaws typically require individual ownership, limit subletting, and apply a financial review to every purchase, cash or financed, commonly a debt-to-income ratio in the mid-to-high twenties and one to two years of post-closing liquidity. The mansion tax is identical for both, rising from 1% at $1M to 3.9% at $25M and above.
The general comparison is in the co-op versus condo primer. This article covers the questions that surface only at the top of the market: buying in an entity, second-home policies, board financial standards, sublet rights, financing flexibility, and privacy.
I was principal broker at Montilla's 159 Real Estate for 15 years before joining Keller Williams NYC in 2016, and in 25+ years selling NYC real estate the costly surprise at this price point is a buyer choosing the apartment first and learning the building's rules second.
The one structural fact everything else follows from
A condo is real property. You take a deed and the apartment is yours the way a house would be. A co-op is not real property. A corporation owns the building, you buy shares in that corporation, and those shares come with a proprietary lease giving you the right to occupy your unit. Every rule below traces back to that one difference. The corporation can set conditions on who holds its shares. A condominium, holding only a bundle of bylaws, has far less room to.
Can you buy it in an LLC or a trust?
This is usually the first real fork in the road. Most NYC condominiums will accept a purchase by a limited liability company, a corporation, or a trust, often with a personal guaranty from the individual behind the entity and a requirement that a named person be identified as the occupant. Most co-ops will not accept an LLC at all. Trust ownership is more commonly permitted in co-ops than LLC ownership, and buildings that allow it typically require the trust beneficiary to be approved as an individual, to sign an occupancy agreement, and to remain personally liable for the maintenance. The disclosure and filing side of entity ownership, including New York's 2019 LLC member disclosure at closing, is covered in buying a NYC apartment through an LLC or trust.
None of this is uniform. Two buildings on the same block can hold opposite positions, and the answer lives in the co-op's transfer policy or the condominium's bylaws, not in a general rule. Read the document before you make the offer. For the mechanics of setting up and funding the entity itself, that is a conversation for your attorney and your accountant, and NYS rules require a broker to give you a list of attorneys to choose from rather than a single name.
The FinCEN reporting rule, and where it stands right now
FinCEN's Residential Real Estate Rule applies to non-financed transfers of residential property to a legal entity or a trust. It expressly reaches transfers of an ownership interest in a cooperative housing corporation, so a co-op share transfer is not outside its scope. Reports were required for closings on or after March 1, 2026.
On March 19, 2026, a federal court in the Eastern District of Texas vacated the rule. FinCEN, with the Department of Justice, has appealed. While that order remains in force, reporting persons are not required to file and are not subject to liability for not filing. Because an appeal is pending, confirm the status with your attorney at contract.
What the public record shows after you close
A condo sale produces a recorded deed, and once it is in ACRIS anyone can see the unit, the parties, and the price. A co-op sale produces no deed, because shares are personal property, so none is recorded.
The transfer tax return is still filed, and it is public. Co-op transfers show up in ACRIS under a real property transfer tax document class rather than a deed, and that filing names the parties and states the consideration. A co-op therefore changes the document type, not the public visibility. Our guide to searching ACRIS walks through exactly what turns up for each.
Buying Above $1M in New York City?
I read the transfer policy and the bylaws before my clients write the offer, so the building's rules on entities, second homes, and subletting are known facts rather than closing-week surprises. Some of the deals I have closed are at miltoncoste.com/listings.
Second homes: who is allowed to leave the apartment empty
If the apartment will not be a primary residence, the building's occupancy rules decide the question. Many co-ops restrict or prohibit pied-a-terre ownership outright. Condominiums are generally more accommodating to part-time occupancy.
Buildings that do permit part-time use often attach conditions: the unit cannot sit vacant indefinitely, family use may be restricted to named relatives, and the board may require notice of extended absences. If a second home is the plan, read our pied-a-terre buying guide before you tour. On the tax side, the annual pied-a-terre surcharge passed the State Legislature on May 27, 2026, and its threshold is measured against the Department of Finance valuation rather than the sale price. The guide above carries the rate table and the exemption paths.
The financial test a board applies to an all-cash buyer
Paying cash does not remove a purchase from co-op board review. Market practice across NYC co-ops clusters around a debt-to-income ratio in the mid-to-high twenties and post-closing liquidity of roughly one to two years of mortgage and maintenance payments held in reserve after the purchase. Those are conventions, not statutes, and plenty of buildings have no written policy.
A co-op board package documents liquid assets, income and reserves with statements, so the review reads from paper. Closely held business interests, restricted stock, and illiquid partnership stakes take longer to document than cash and marketable securities, so allow extra time and see the co-op purchase process for the steps. A condominium application is an information exercise attached to a right of first refusal, not a financial review.
Renting it out later: sublet caps and right of first refusal
Co-op sublet policies are typically written as a formula. A common structure is a required owner-occupancy period of about two years, followed by permission to sublet for a limited number of years within a rolling window, with board approval of each tenant and a sublet fee paid to the corporation. Some buildings cap the percentage of units that may be sublet at one time, so a sublet can wait in a queue.
Condominium boards generally cannot block a rental. Most NYC condo bylaws instead give the board a right of first refusal: the board may buy the unit on the same terms rather than approve or reject your tenant. In practice boards rarely exercise it, so a condo is the default structure for a buyer who wants the option to hold and rent.
Closing math: mansion tax, flip tax, and transfer taxes
The mansion tax applies identically to both structures. It is buyer-paid, starts at 1% on residential purchases of $1M or more, and steps up through progressive brackets to 3.9% at $25M and above, applied to the entire purchase price rather than only the amount over the bracket threshold. Our complete mansion tax guide lays out every tier and the cliff effect at each one.
The two structures diverge on the resale side, a cost inherited at purchase.
Cost
Co-op
Condo
Mansion tax (buyer)
1% to 3.9% by bracket, $1M and up
Same
NYC transfer tax (seller, residential over $500K)
1.425%
1.425%
NY State transfer tax (seller)
0.4%, rising to 0.65% at $3M
Same
Flip tax on resale
Common. Typically 1% to 3% of price, most often 2%, usually seller-paid
Uncommon. New developments often charge the buyer a capital contribution instead
Mortgage recording tax
Not applicable, a co-op loan is not a mortgage on real property
Applies
On a $3M resale, a 2% co-op flip tax is $60,000 that a comparable condo seller would not pay. On the buy side, the absence of mortgage recording tax on a financed co-op purchase cuts the other way. Run both numbers against your expected hold period rather than assuming one structure is cheaper. The flip tax guide covers how the different formulas are calculated, and the closing cost breakdown shows where each line lands.
Financing flexibility at the top of the market
Co-op corporations set their own maximum financing percentage, and many high-end buildings require substantially more than 20% down. Some permit no financing at all. A condominium leaves the loan question between buyer and lender, so portfolio lending, cross-collateralized structures tend to be simpler there. Confirm the building permits your loan structure before contract, because a co-op can decline a financing arrangement the lender has already approved.
What each structure allows, by use
Condo structure
• Title can be held by an LLC, a corporation, or certain trusts
• Second-home or part-year use is generally permitted
• Renting is not subject to board approval of the tenant
• Complex or portfolio-style financing is available
Co-op structure
• Ownership is shares in a corporation plus a proprietary lease
• Prewar buildings often trade at a discount to comparable condos
• The financial package documents liquid assets
A condo buys optionality, and a co-op prices it through review, restrictions, and a flip tax on the way out. For a long-term primary residence, the co-op discount is real money. For an apartment that must hold an entity, sit empty for stretches, or produce rent, the condo premium pays for a structure that permits it.
Let's Match the Structure to Your Plan
I represent buyers across all five boroughs and the Hudson Valley, in English and Spanish. Tell me how you intend to use the apartment and I will tell you which buildings will actually allow it.
Send the address you are looking at. The report covers what the listing leaves out: the recorded sale history, the tax and abatement picture, open building violations and permits, and the closed sales that set the price. Milton prepares it from public records. No obligation.
Get NYC market insights delivered to your inbox
New listings, market data, and expert analysis. No spam.